Home insurance written for Northeast Ohio houses
Century-old colonials, slate roofs and finished basements need more than a generic policy. We read the endorsements so a lake-effect winter does not become a denied claim.
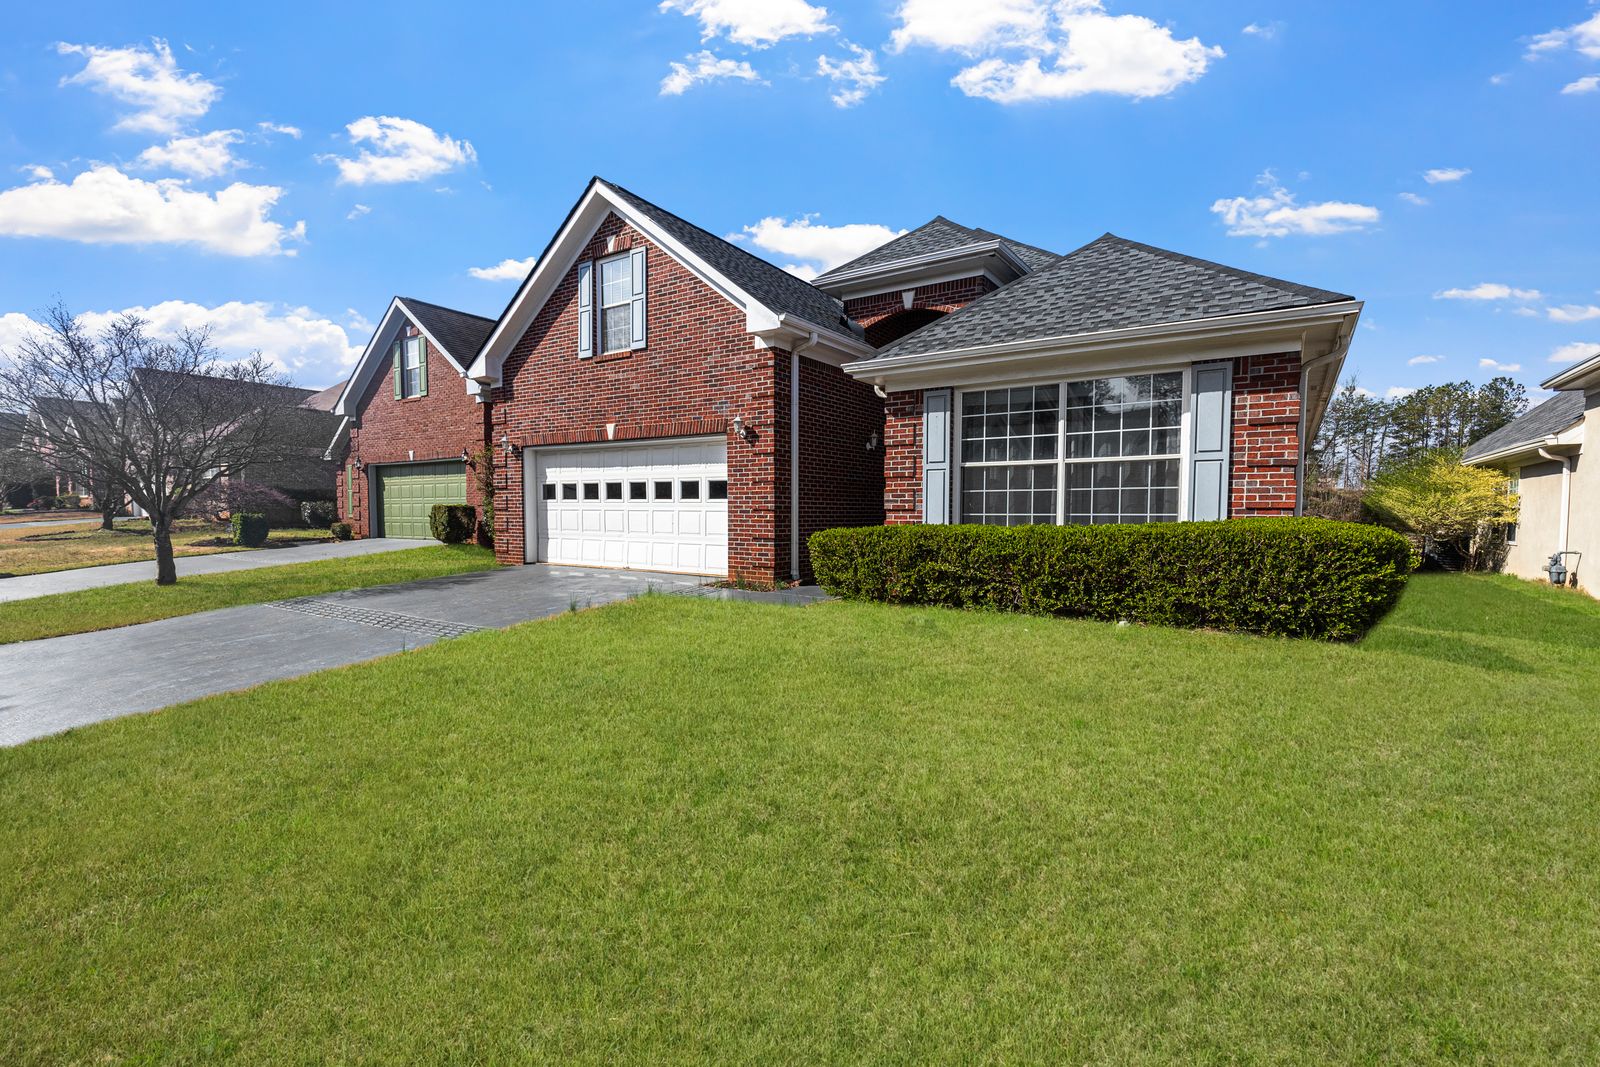
How we approach home insurance
Most Cleveland-area homes were built before 1960. That matters for replacement cost, for older wiring and plumbing, and for roofs that carriers now depreciate aggressively. We start with an accurate rebuild estimate, not the purchase price or the tax value, so your dwelling limit is realistic.
The gaps we see most are sewer and drain backup, which standard policies exclude, and roof coverage that pays only depreciated value. We check both on every quote and show you what adding or changing them costs across carriers.
What a typical policy includes
Dwelling
Rebuilds the structure after fire, wind, hail, ice dams and other covered losses.
Other structures
Detached garages, fences and sheds, usually at 10 percent of the dwelling limit.
Personal property
Furniture, clothing and electronics, ideally at replacement cost rather than depreciated value.
Loss of use
Hotel, rental and extra living costs while your home is being repaired.
Personal liability
Injuries to guests and damage you accidentally cause to others, with legal defense.
Water backup endorsement
Covers sewer and sump pump backups, the most common basement claim in the region.
What affects your price
Carriers weigh these differently, which is exactly why comparing several of them pays off.
| Factor | Why it matters |
|---|---|
| Roof age and material | Roofs older than 15 years may be written at actual cash value. |
| Rebuild cost | Square footage, finishes, plaster walls and local labor rates. |
| Claims history | Water and wind claims on the property or by you in the last five years. |
| Protection class | Distance to a fire hydrant and the rating of the local fire department. |
| Deductible | A $2,500 deductible instead of $1,000 can lower premium noticeably. |
| Updates | Electrical, plumbing and heating updates in the last 25 years help. |
Replacement cost or actual cash value: the endorsement that decides a hail claim
One line on the declarations page separates a new roof from a cheque for a third of one. Drag the age of your roof and watch the settlement move.
- Roof age
- 12 years
- Actual cash value settlement
- $10,648
- Replacement cost settlement
- $21,400
- What you fund yourself under actual cash value
- $10,752
Depreciated payout, after your $1,000 deductible.
Paid in two parts: actual cash value first, the withheld depreciation once the work is done and invoiced.
Sample figures: $22,400 tear-off and replacement on a 1,940 sq ft roof, 25 year architectural shingle, straight-line depreciation, $1,000 deductible.
| Roof age | ACV cheque | RCV cheque | Your gap |
|---|---|---|---|
| 3 yrs | $18,712 | $21,400 | $2,688 |
| 8 yrs | $14,232 | $21,400 | $7,168 |
| 12 yrs | $10,648 | $21,400 | $10,752 |
| 16 yrs | $7,064 | $21,400 | $14,336 |
| 20 yrs | $3,480 | $21,400 | $17,920 |
- Several carriers now move roofs past 15 years onto actual cash value automatically at renewal, without a premium change. The endorsement is the only place it shows.
- Read the declarations page for "windstorm or hail loss to roof surfacing" and for a separate percentage wind and hail deductible.
- Keeping replacement cost on an older roof typically costs $60 to $140 a year. It is the cheapest large claim you will ever buy back.
From first call to coverage in about a day
Most personal policies can start within one business day. Commercial lines usually take three to five.
- 1
Tell us the basics
Five minutes online or on the phone. A photo of your current declarations page is plenty.
- 2
We shop the carriers
Your agent runs the same coverage across the carriers that write this line well.
- 3
Compare with an agent
A short call to walk through price, limits and the fine print that actually differs.
- 4
Bind and stay covered
We start coverage, send documents, and re-check it at every renewal.
Why clients buy home insurance through Ironbridge
Accurate rebuild estimates
We use replacement cost tools, not the listing price, to set the dwelling limit.
Roof terms explained
You will know whether a hail claim pays full replacement or a depreciated amount.
Bundle pricing
Home and auto together often save 15 to 25 percent with our carriers.
Mortgage paperwork handled
We send evidence of insurance to your lender and title company directly.
Home insurance questions
More answers in our full FAQ, or call an agent at (216) 555-0117.
Water that backs up through a drain or sump pump is covered only with a water backup endorsement. Surface flooding from rising water requires a separate flood policy. We quote both.
Enough to rebuild the house at today's construction costs, which can be higher or lower than the market value. We calculate this with you during the quote.
Standard policies cap theft of jewelry, often at $1,500. Scheduling valuable items raises that limit and usually removes the deductible.
Yes. You receive a prorated refund from the old carrier. We coordinate the start date and notify your mortgage company.
Often paired with home insurance
Compare home insurance quotes today
One conversation, quotes from up to 14 carriers, and an agent who explains the trade-offs before you sign.
Licensed agents · No fee for advice · 4.9 from 1,284 reviews