Commercial auto for the vehicles that keep you working
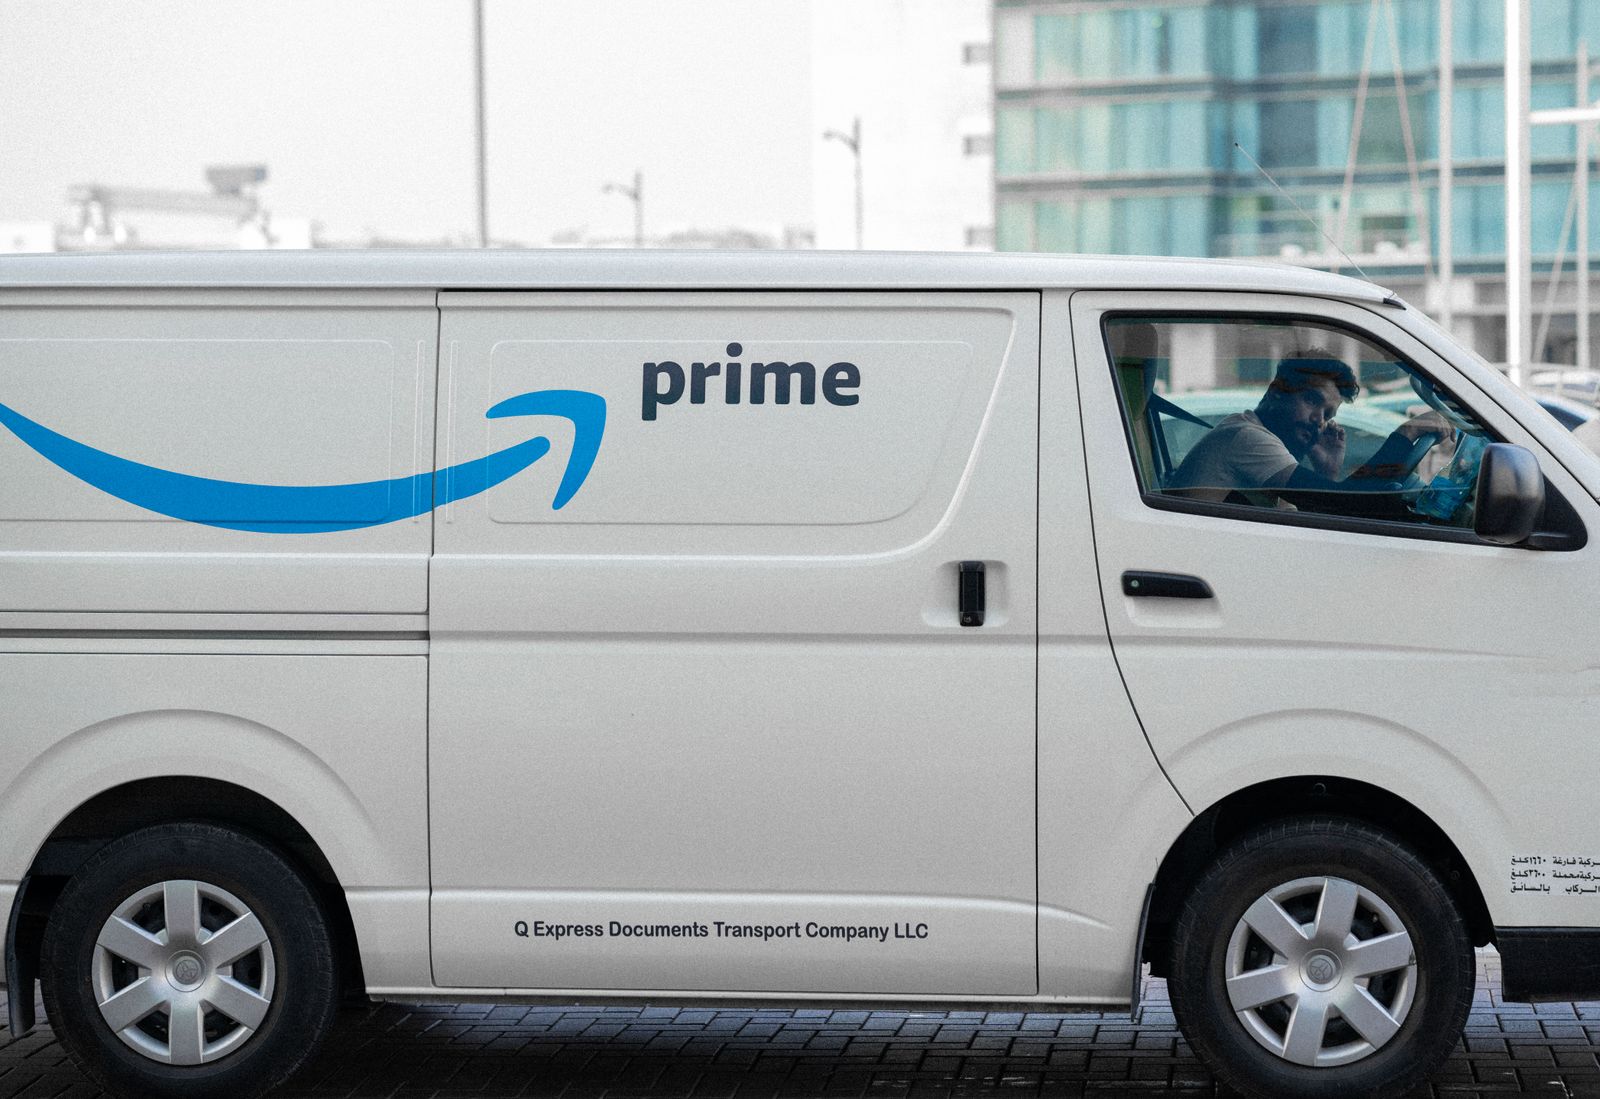
Personal auto policies exclude most business use. If your truck hauls tools, your van makes deliveries or employees drive for you, you need commercial coverage.
How we approach commercial auto insurance
A personal auto policy can deny a claim if the vehicle was used primarily for business, carried signage, or was driven by an employee. Commercial auto closes that gap and allows higher liability limits, often $1 million, which general contractors and property managers frequently require.
We write single-vehicle policies for owner operators and fleets up to about 50 units. Driver lists, vehicle radius, cargo and upfitted equipment such as ladder racks and shelving all affect pricing, and we make sure they are listed correctly from the start.
What a typical policy includes
Commercial liability
Bodily injury and property damage at limits up to $1 million combined single limit.
Physical damage
Collision and comprehensive for owned work vehicles.
Hired and non-owned auto
Rentals and employee-owned vehicles used for business.
Uninsured motorist
Protection when the at-fault driver cannot pay.
Upfit and equipment coverage
Racks, shelving, lift gates and permanently attached tools.
Rental reimbursement and towing
Keep jobs moving while a vehicle is repaired.
What affects your price
Carriers weigh these differently, which is exactly why comparing several of them pays off.
| Factor | Why it matters |
|---|---|
| Vehicle type and weight | Light vans rate differently than box trucks. |
| Use and radius | Local service calls versus regional hauling. |
| Driver records | Every listed driver's motor vehicle report. |
| Industry | Contractors, delivery and catering carry different risk. |
| Limits and deductibles | $1M liability versus $500k, and physical damage deductibles. |
From first call to coverage in about a day
Most personal policies can start within one business day. Commercial lines usually take three to five.
- 1
Tell us the basics
Five minutes online or on the phone. A photo of your current declarations page is plenty.
- 2
We shop the carriers
Your agent runs the same coverage across the carriers that write this line well.
- 3
Compare with an agent
A short call to walk through price, limits and the fine print that actually differs.
- 4
Bind and stay covered
We start coverage, send documents, and re-check it at every renewal.
Why clients buy commercial auto insurance through Ironbridge
Driver onboarding help
We check a new hire's MVR before they get behind the wheel.
Fleet certificates
Auto ID cards and certificates for every unit, sent in one batch.
Coordinated with your BOP
No gaps between commercial auto and general liability.
Safety program credits
Some carriers discount telematics and written driver policies.
Commercial auto insurance questions
More answers in our full FAQ, or call an agent at (216) 555-0117.
Often yes, especially if you carry tools or equipment, the vehicle is titled to the business, or employees drive it. We review your use and give you a clear answer.
Yes. Send us the VIN and we can add it the same day and email updated ID cards.
It covers liability when you or employees use rented or personal vehicles for business errands. It is inexpensive and frequently overlooked.
Often paired with commercial auto insurance
Business owners policy
Property and general liability packaged for shops, offices, restaurants and contractors.
Workers' compensation
Ohio BWC setup and guidance, plus employer's liability and stop gap coverage.
Auto insurance
Liability, collision and comprehensive for Ohio drivers, shopped across our carriers.
Compare commercial auto insurance quotes today
One conversation, quotes from up to 14 carriers, and an agent who explains the trade-offs before you sign.
Licensed agents · No fee for advice · 4.9 from 1,284 reviews